arXivEconometrics & Forecasting
A Stochastic Nested Fixed Point Algorithm for Large-Scale BLP Estimation
A stochastic nested fixed-point estimator reduces memory and computational cost for random-coefficients logit demand models, enabling estimation on 100 million markets in hours.
Featured in No. 132 on 25 Sep 2026 · 3 days after release · 0 citations today
- Released
- 22 Sep 2026
- First featured
- No. 132 · 25 Sep 2026
- Citations (Semantic Scholar)
- 0
- Influential citations
- 0
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- arXiv:2609.23998
- Authors
- Zhentong Lu et al.
Abstract
From arXiv (CC0).
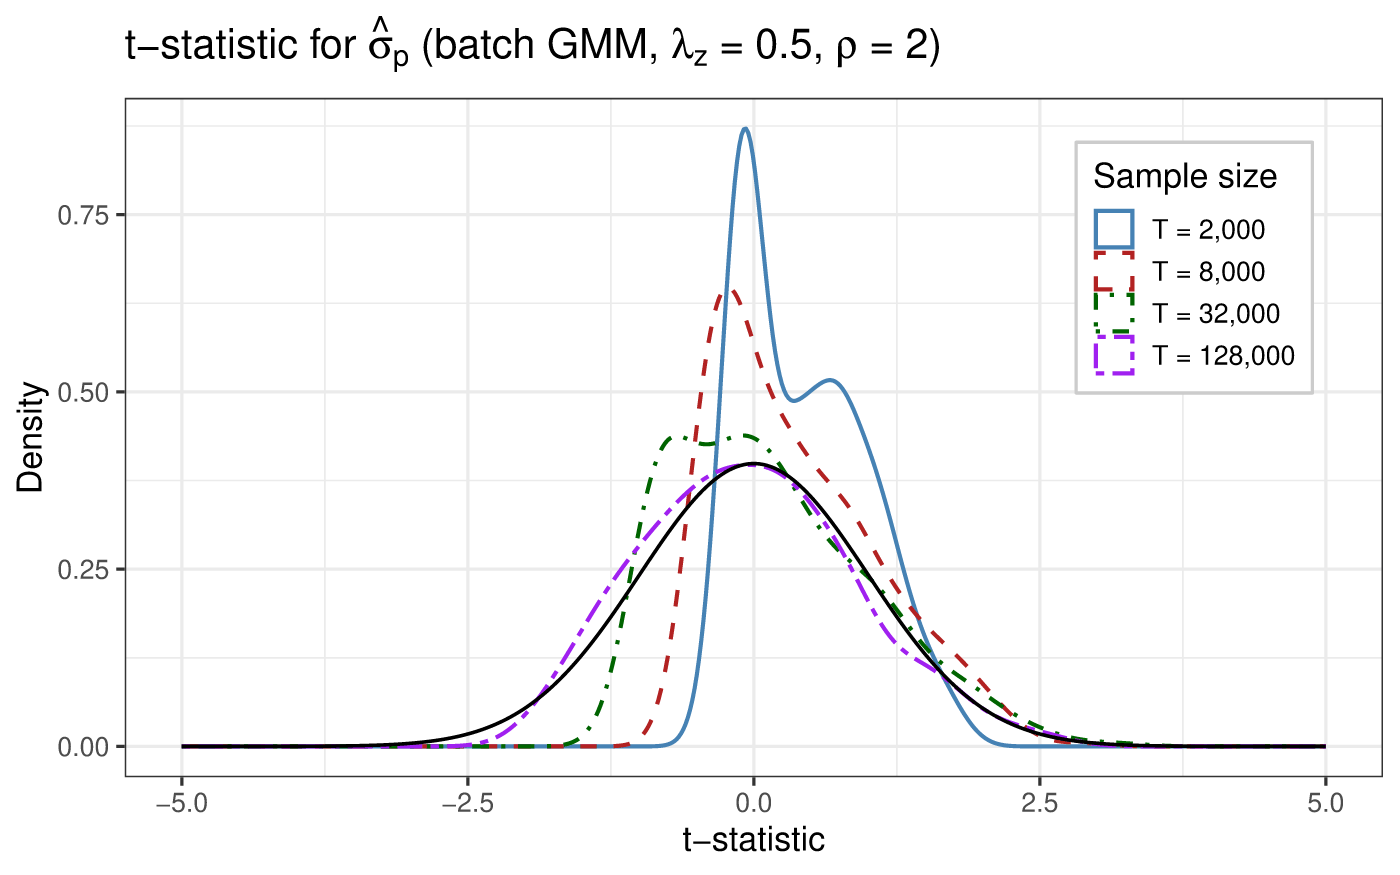
We develop a stochastic nested fixed point (SNFP) estimator for random coefficients logit demand models that updates model parameters using stochastic gradients and performs demand inversion one market at a time. Relative to the conventional nested fixed point (NFP) estimator, SNFP substantially reduces memory requirements and computational cost, making estimation feasible in very large datasets. We establish the large-$T$ (number of markets) asymptotic properties of the estimator under regularity conditions. We also characterize the effect of sharing one block of simulation draws across markets and show how to correct for it. Monte Carlo simulations show that the SNFP estimator achieves statistical accuracy comparable to the NFP estimator, and in our benchmark a single online pass estimates a model with 100 million markets in about 5.5 hours. An empirical application using scanner data further demonstrates the practical advantages of SNFP for large-scale demand estimation.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).