arXivEconometrics & Forecasting
Network Realized GARCH--Itô Models: Volatility Spillovers with High-Frequency Identification
Introduces a network realized GARCH-Itô model that identifies dynamic volatility transmission among assets using high-frequency data, outperforming recursive forecasts on sector ETFs.
Featured in No. 132 on 25 Sep 2026 · on release day · 0 citations today
- Released
- 25 Sep 2026
- First featured
- No. 132 · 25 Sep 2026
- Citations (Semantic Scholar)
- 0
- Influential citations
- 0
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2609.29515
- Authors
- Xinyu Song
Abstract
From arXiv (CC0).
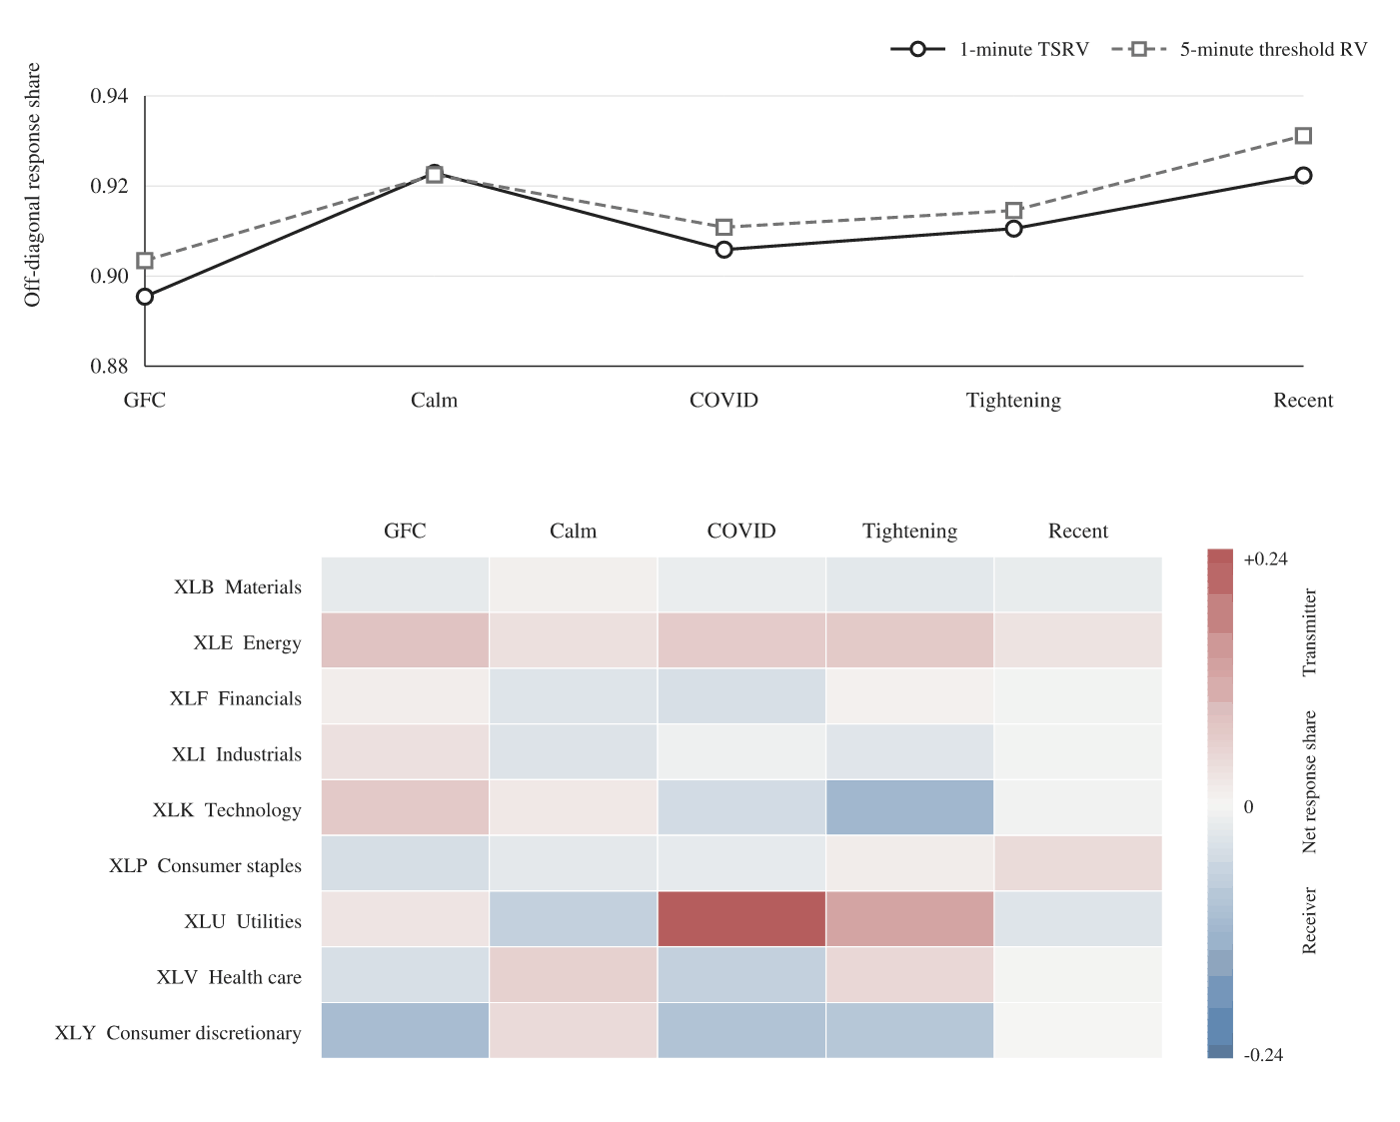
We introduce a network realized GARCH-Itô model in which volatility transmission is a dynamic relation among the latent daily integrated volatilities of multiple assets. An unknown directed and signed network is embedded in a continuous-time variance process and appears in the resulting exponential daily recursion. Intraday returns identify integrated volatility and hence the network that governs its propagation. For a fixed network template, feasible estimation based on realized volatility is first-order equivalent to estimation based on latent integrated volatility. For an unknown network, regularization selects the relevant structure, and, under oracle conditions, a fixed-rank local refit provides conditional inference for model-implied response-based connectedness. In an application to nine U.S. sector ETFs from 2007 to 2025, the model attains the lowest average out-of-sample QLIKE among the reported recursive forecasts, although its advantage over HAR is not statistically significant. In the full sample the weighted LASSO selects an empty sparse support, so inference concerns the rank-one projected factor component; this conditional analysis identifies Energy as a net volatility transmitter. Aggregate connectedness is more stable across volatility measures than individual sparse channels.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).