RePEcML & AI Methods
Assessing the Benefits of Optimized Agentic AI Systems for Asset Pricing
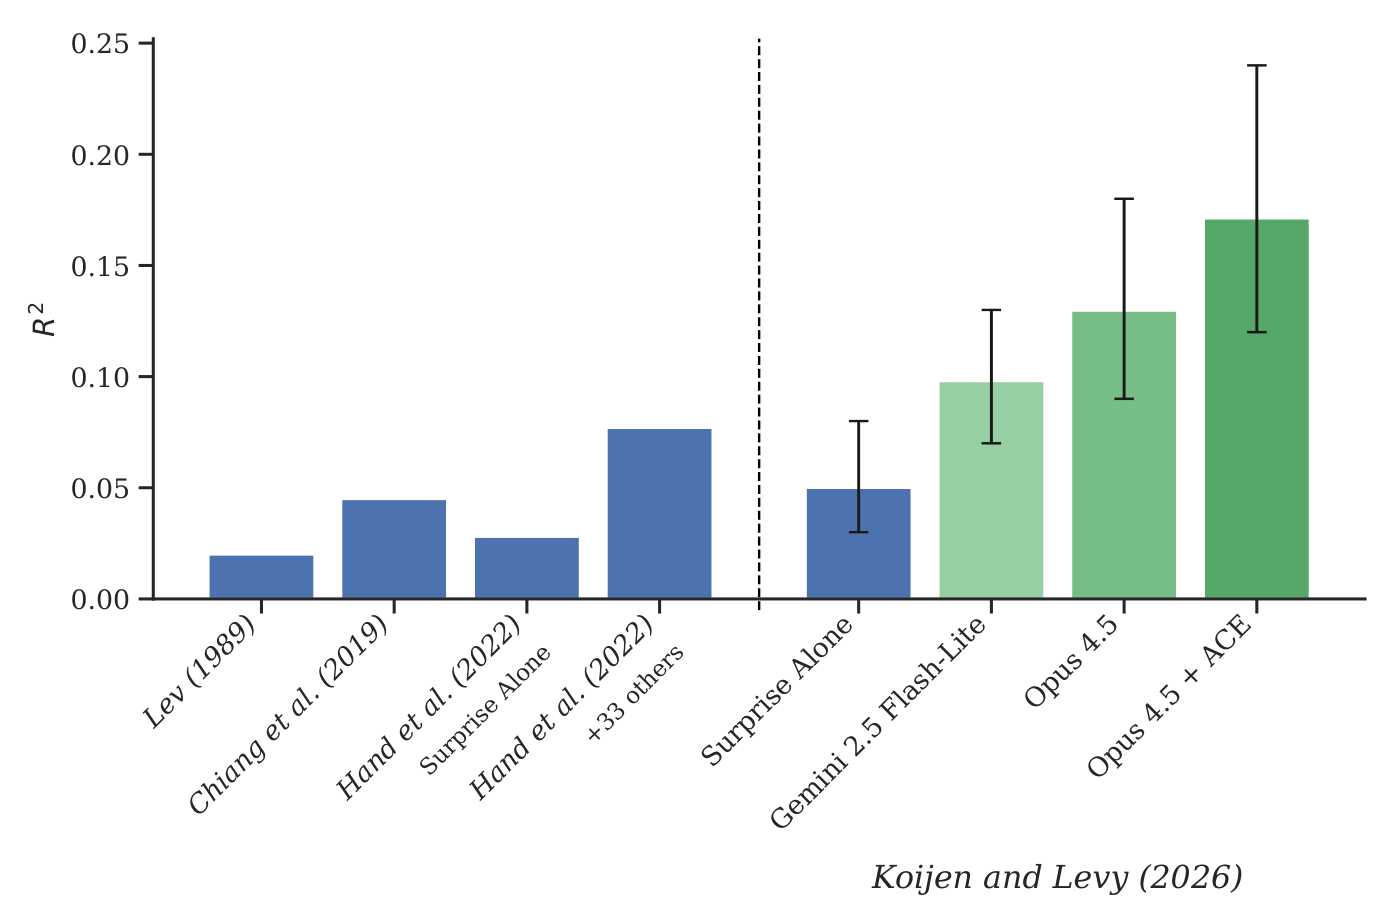
Optimized AI systems analyzing earnings call transcripts double explained variation in stock returns versus standard benchmarks while improving interpretability through human-readable decision rules.
Featured in No. 132 on 25 Sep 2026 · 8 days after release
- Released
- 17 Sep 2026
- First featured
- No. 132 · 25 Sep 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 4 of 5
- Identifier
- RePEc:nbr:nberwo:35431
- Authors
- Ralph S. J. Koijen and Bradford Levy
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).