Rate Risk and Rate Insurance
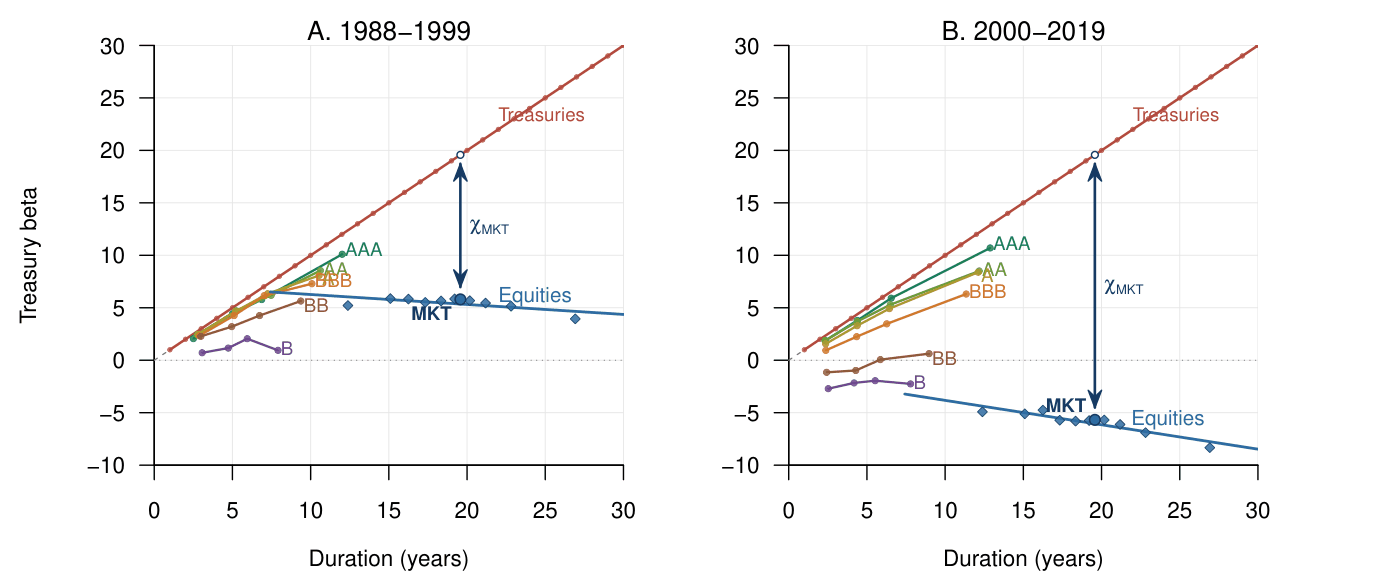
Stock returns are dampened by rate insurance: falling rates cushion payoff risk in bad times while rising rates in good times hedge duration exposure.
Featured in No. 132 on 25 Sep 2026 · 12 days after release
- Released
- 13 Sep 2026
- First featured
- No. 132 · 25 Sep 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:nbr:nberwo:35636
- Authors
- Olivier Wang
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).