Pricing Risk Globally: Intermediary Constraints, the Dollar, and the Global Financial Cycle
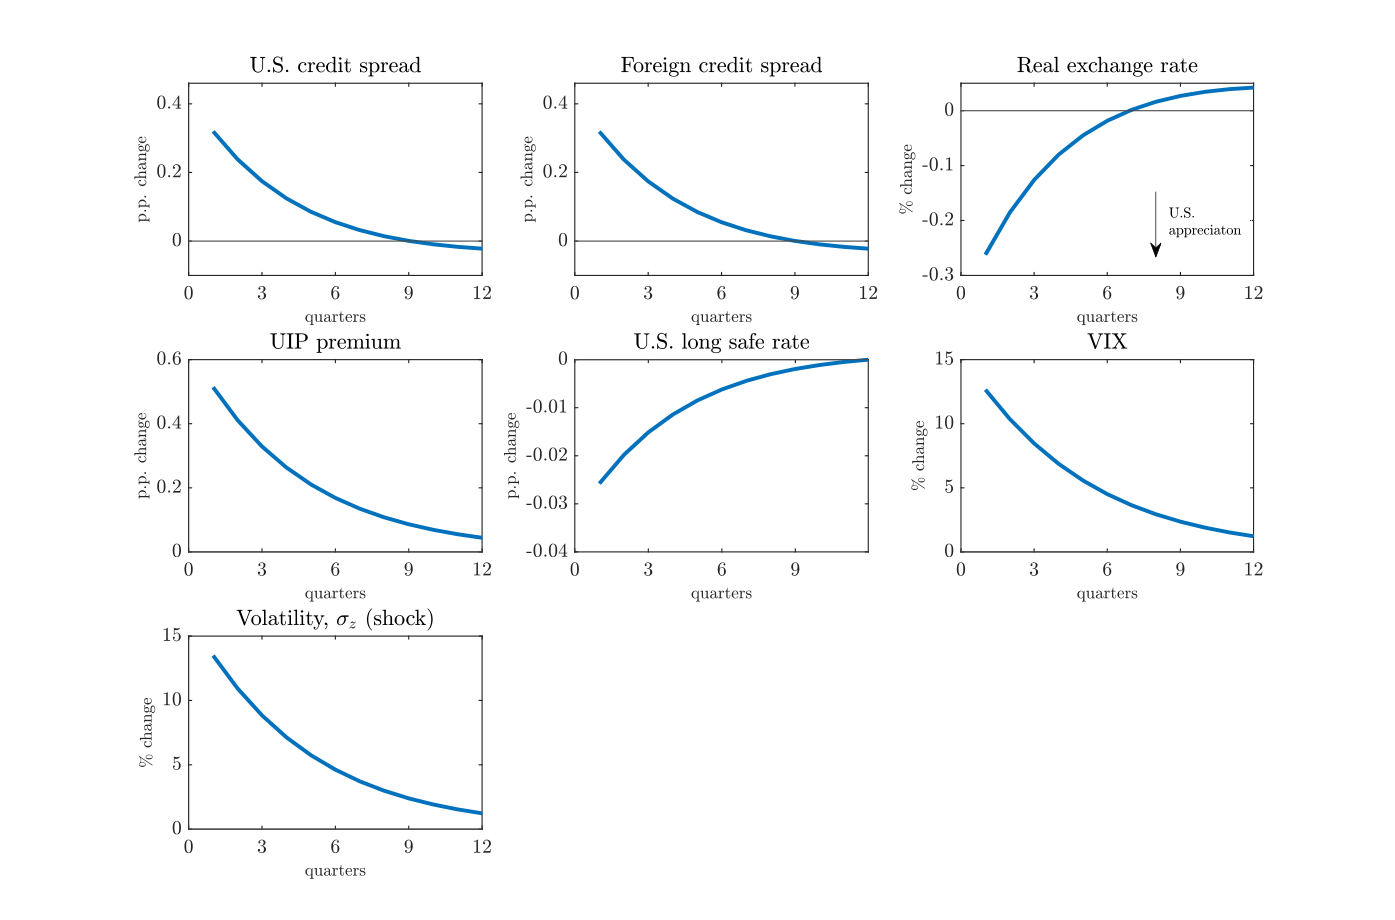
A two-country model shows that uncertainty shocks tighten intermediary constraints, widening credit spreads, appreciating the dollar, and raising currency risk premia globally.
Featured in No. 132 on 25 Sep 2026 · 11 days after release
- Released
- 14 Sep 2026
- First featured
- No. 132 · 25 Sep 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:fip:fedgif:103716
- Authors
- Ozge Akinci and Ṣebnem Kalemli-Özcan
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).