Common Risk Factors in the Returns on Stocks, Bonds (and Options), Redux
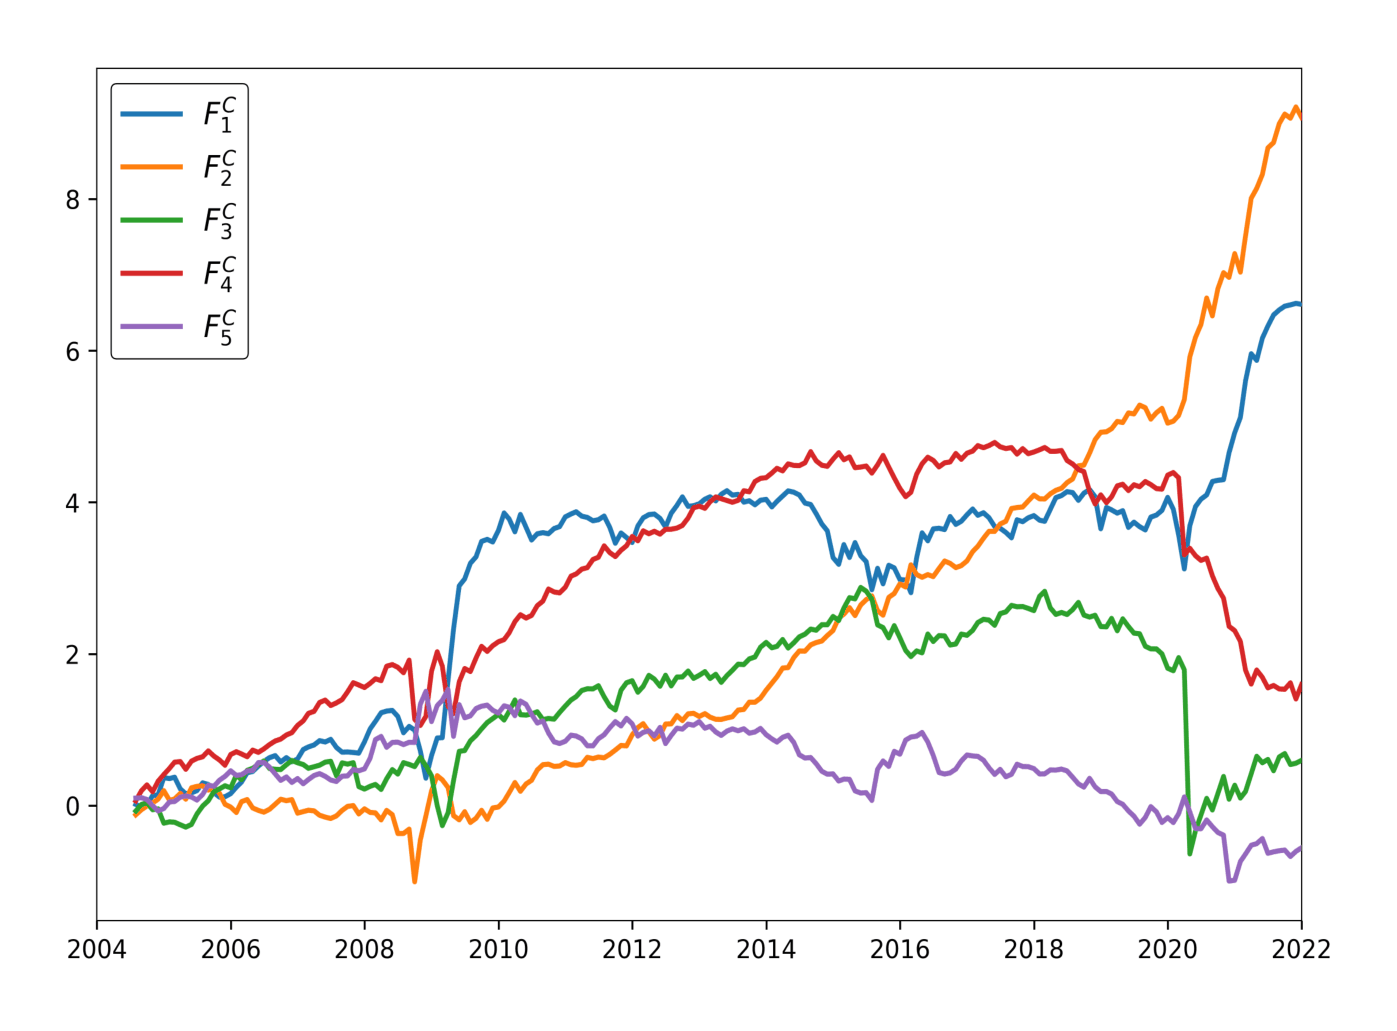
The research identifies common risk factors spanning stocks, corporate bonds, and options linked to economic indicators, revealing significant market segmentation and cross-asset hedging opportunities.
Featured in No. 132 on 25 Sep 2026 · 12 days after release
- Released
- 13 Sep 2026
- First featured
- No. 132 · 25 Sep 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:nbr:nberwo:35579
- Authors
- Zhongtian Chen et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).